
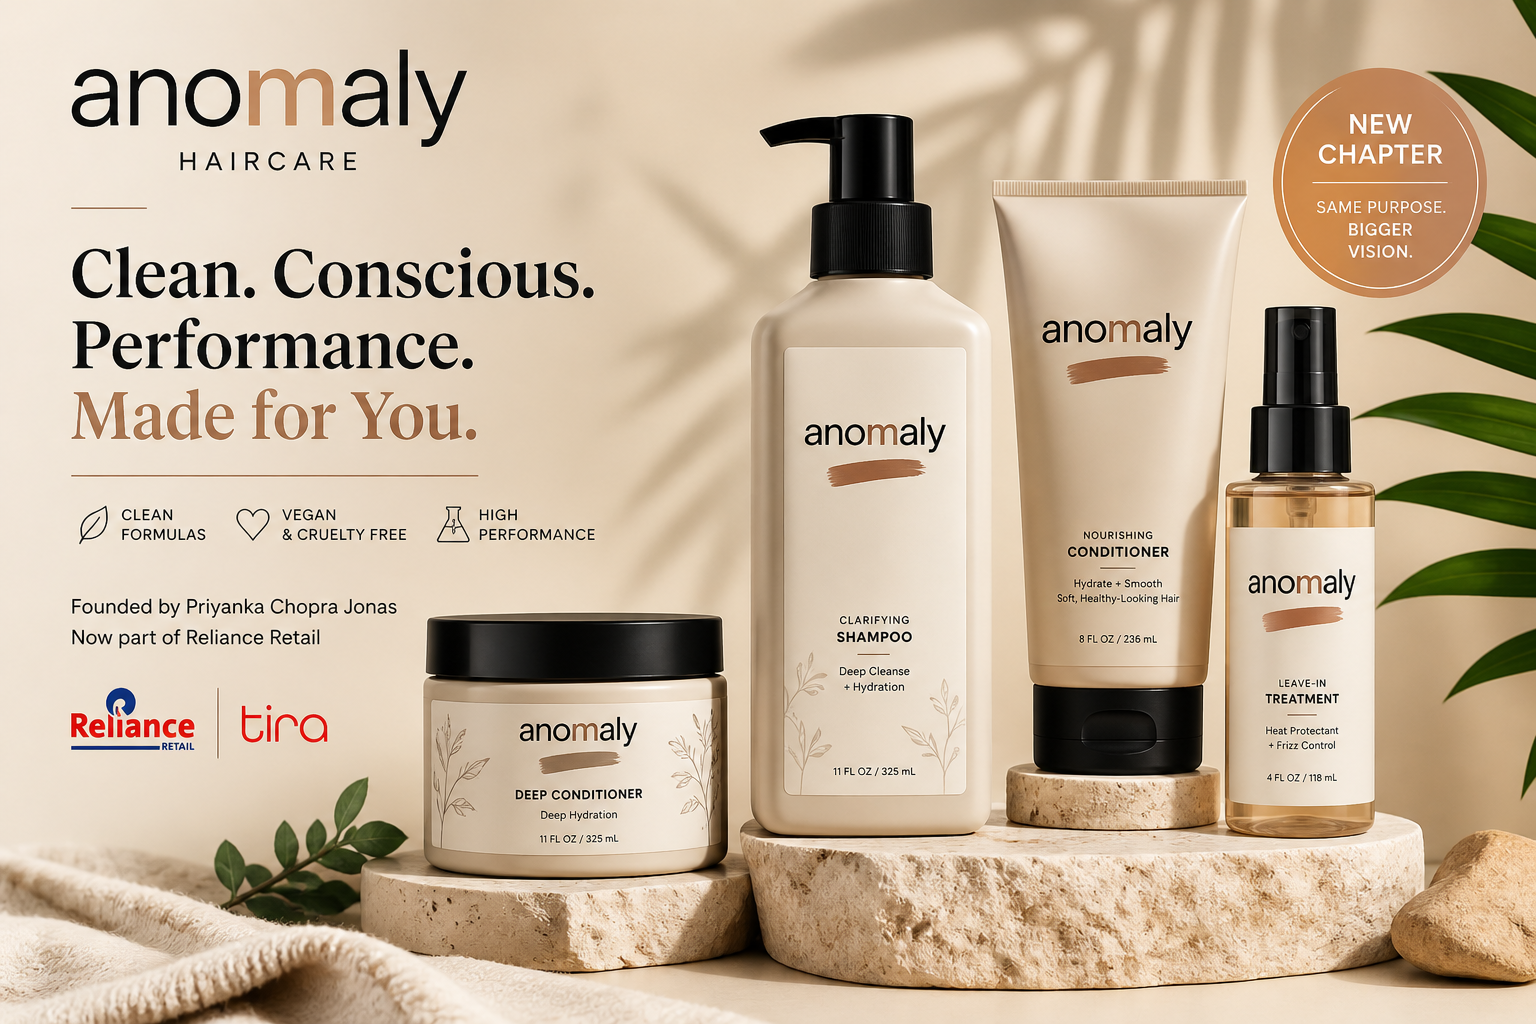
When Reliance Retail Ventures Limited (RRVL) completed its acquisition of Anomaly Haircare—the clean, vegan personal care label co-founded by international star and entrepreneur Priyanka Chopra Jonas—financial coverage framed the deal as a conventional trophy consolidation. Press narratives highlighted Chopra Jonas’s global celebrity profile, the brand’s rapid cross-border footprint across the United States and India, and its accessible clean-formulation thesis as immediate validation of commercial dominance.
+---------------------------------------------------------------------------------+
|                         DEAL FACT SHEET: ANOMALY HAIRCARE                       |
+----------------------+----------------------------------------------------------+
| Target Asset         | Anomaly Haircare (Global Trademarks, IP, Digital Assets) |
| Target Co-Founder    | Priyanka Chopra Jonas (developed in incubator model)     |
| Acquiring Entity     | Reliance Retail Ventures Limited (RRVL)                  |
| Deal Structure       | Full commercial buyout of IP and digital properties;     |
|                      | founder transitions to Creative Director                 |
| Retained Leadership  | Priyanka Chopra Jonas: Creative Director & Vision        |
| Operational Control  | Integrated into Reliance omnichannel distribution system |
+----------------------+----------------------------------------------------------+
An examination of corporate balance sheets shows a far more nuanced operational picture. The Anomaly acquisition is not an ordinary licensing agreement; it is an instructive case study in the structural lifecycle of direct-to-consumer (D2C) brands. It illustrates what occurs when high digital attention collides with the physical requirements of consumer packaged goods (CPG): retail distribution depth, rising packaging raw material costs, hypermarket slotting fees, and working capital limits.
For Reliance Retail, this transaction represents an asset-light, intellectual-property-heavy addition to its expanding house-of-brands. Rather than acquiring distressed legacy production plants or high corporate overhead, Reliance acquired registered global trademarks, chemical formulations, and established consumer goodwill.
For Priyanka Chopra Jonas, the transaction represents a strategic transfer of operating risk. By stepping out of operational administration and assuming the role of Creative Director, she preserves brand identity and formulation standards while handing over supply-chain logistics, distribution channels, and inventory risk to an integrated enterprise balance sheet.
For related analyses on consumer brand acquisitions, explore our hub at All Marketing Updates Case Studies.
Anomaly’s Trajectory: The Divergence of Paper Valuation and Operating Reality
Launched in early 2021, Anomaly entered the personal care space to challenge a fundamental pricing imbalance: effective, clean, sulfate-free haircare was priced as a luxury category out of reach for mass-market shoppers.
+--------------------------------------------------------------------------+
|                     ANOMALY'S ORIGINAL MARKET PLAYBOOK                   |
|                                                                          |
|  • Accessible Price Point: Sub-$6 per unit across US hypermarkets        |
|  • Clean Formulation: Sulfate-free, paraben-free, vegan chemistry        |
|  • Eco-Packaging: 100% Post-Consumer Recycled (PCR) plastic              |
|  • Mass Channel Partner: Exclusive Target retail rollout (US)            |
|  • Subcontinent Debut: Direct platform entry via Nykaa and Myntra (2022) |
+--------------------------------------------------------------------------+
The $6 Mass-Market Proposition
Rather than adopting the high-margin playbook of prestige celebrity beauty—pricing 250ml bottles between $30 and $48—Anomaly launched with an aggressive mass-market entry point: under $6 per unit at retail.
To protect unit economics at this price point, the brand stripped away decorative secondary packaging:
- Bottles were molded from 100% post-consumer recycled (PCR) resin sourced from ocean-bound and landfill waste streams.
- Thin-walled, cylindrical silhouettes reduced resin weight and tooling expenses.
- Formulations avoided expensive aesthetic texturizers, prioritizing sulfate-free, vegan formulas that met clean-beauty standards.
Chopra Jonas brought personal credibility to this positioning, openly discussing how decades of chemical styling on international film sets highlighted the need for accessible, restorative hair products.
The Disconnect Between Industry Rankings and Operational Scale
By 2023, beauty benchmark index Cosmetify ranked Anomaly as the second most valuable celebrity beauty brand in the world, behind only Rihanna’s Fenty Beauty and ahead of Selena Gomez’s Rare Beauty and Kylie Jenner’s Kylie Cosmetics.
+---------------------------------------------------------------------------+
|              THE VALUATION-TO-REVENUE PARADOX (2023–2026)                 |
|                                                                           |
|   Cosmetify Index (2023):             Actual Global Revenue (2024):       |
|   #2 Most Valuable Celebrity Brand    ~$50 Million (Top-Line Gross)       |
|                                                                           |
|   Standalone US Entity (2026):        Operating Margin Pressures:         |
|   Corporate Operations Wound Down     Sub-$6 price point eroded by        |
|                                       input inflation & logistics         |
+---------------------------------------------------------------------------+
The underlying metrics, however, revealed a widening divide between digital visibility and operational sustainability:
- Modeled Valuations vs. Realized Enterprise Value: The 2023 industry index relied on digital proxies—search volumes, social sentiment, potential ad equivalency, and modeled enterprise multiples—rather than audited EBITDA or operating cash flow. YouTube
- Top-Line Scale vs. Multinational Competition: In 2024, Anomaly generated approximately $50 million in global top-line revenue. While strong for an independent three-year-old brand, this volume was thin for a low-cost, mass-market consumer product line competing against multinational conglomerates like Unilever, L’Oréal, and Procter & Gamble. YouTube+ 1
- The Dissolution of the Standalone US Operating Entity: By early 2026, the standalone US corporate structure housing Anomaly’s independent operations wound down. Managing independent hypermarket distribution in North America, combined with packaging inflation and private-label competition, strained standalone working capital.
To understand how direct-to-consumer businesses hit growth plateaus, read our deep-dive on Advertising & Strategy Trends.
The Mechanical Bottleneck: Why Audience Cannot Substitute for Distribution
The operational friction Anomaly encountered reflects a structural reality across creator-led consumer businesses: celebrity fame is an attention catalyst, not an operating infrastructure.
                   THE CELEBRITY ACCELERATION CEILING

                      FOUNDER AUDIENCE REACH
                                 │
                                 ▼
                     INITIAL SALES SPIKE (DAY 1-90)
                                 │
                                 ▼
                   ┌───────────────────────────┐
                   │THE THREE OPERATING CHOKES │
                   └───────────────────────────┘
                                 │
        ┌────────────────────────┼────────────────────────┐
        │                        │                        │
        ▼                        ▼                        ▼
 1. CAC Inflation         2. Offline Distribution  3. Mass Unit Economics
  Organic reach decays;    Trade spend, slotting    High input inflation
  paid customer spend      fees, out-of-stock       destroys low-margin
  erodes margins           chargeback penalties     accessible SKUs
1. Organic Reach Decay and Paid Acquisition Costs
A celebrity founder with tens of millions of social media followers can generate early sales spikes with minimal initial ad spend. Over time, however, this organic lift inevitably fades:
- Social media platform algorithms limit unpaid organic impressions, forcing brands to run paid campaigns to re-engage their founder’s followers.
- Once early-adopter fans finish their first purchases, customer conversion metrics settle back to normal industry baselines.
- The brand must eventually buy standard programmatic ads across Meta, Google, and short-form video platforms to attract everyday consumers who care about product performance rather than celebrity backing.
2. Physical Retail Distribution and Trade Working Capital
In personal care, between 70% and 80% of total consumer purchases take place inside physical retail stores:
- Hypermarkets, pharmacy chains, and department stores operate on demanding supplier arrangements, including slotting allowances, promotional rebates, return guarantees, and extended payment cycles (60 to 120 days net).
- Retail networks enforce financial chargebacks for delayed shipments, damaged cartons, or out-of-stock shelf placements.
- A celebrity founder cannot resolve regional warehouse bottlenecks, optimize inventory turns, or absorb long cash-conversion cycles.
- When working capital gets tied up in supply shipments or unpaid retailer invoices, digital brand awareness cannot solve the cash crunch. YouTube
3. The Math of Mass-Market Pricing Under Inflation
Anomaly’s sub-$6 retail strategy left no margin for error when macroeconomic conditions shifted:
Gross Margin=MSRP−(Active Ingredients+PCR Packaging+Contract Manufacturing+Freight+Retailer Margin)
When global energy prices, raw chemical ingredients, and packaging materials surged between 2022 and 2024, luxury products retailing for $35 absorbed the cost increases easily. For an accessible brand selling at $5.99, a $0.65 increase in manufacturing and freight costs wiped out operating margins. Without massive packaging volume discounts, the standalone business struggled to sustain its price position.
A Comparative Matrix: Three Indian Celebrity Trajectories
The evolution of India’s creator economy is highlighted by three high-profile ventures, each showing a distinct structural pathway, market positioning, and corporate outcome.
+-----------------------------------------------------------------------------------------+
|                  CELEBRITY VENTURE OUTCOME MATRIX (INDIAN BPC & APPAREL)                |
+----------------------+--------------------+--------------------+------------------------+
| Dimension            | Anomaly Haircare   | Ed-a-Mamma         | 82°E                   |
+----------------------+--------------------+--------------------+------------------------+
| Founder / Face       | Priyanka Chopra    | Alia Bhatt         | Deepika Padukone       |
|                      | Jonas              |                    |                        |
| Category Target      | Clean Haircare     | Sustainable Kids/  | Premium Prestige       |
|                      |                    | Maternity Apparel  | Skincare               |
| Peak/Reported Rev    | ~$50M FY24         | ₹250 Crore         | ₹15.2 Crore FY25       |
|                      | (Global)           |                    | (-36% YoY)             |
| Operating Profit/Loss| Breakeven pressure | Profitable Growth  | -₹12.3 Crore           |
| Status               |                    | Post-Sale          | FY25 Loss              |
| Capitalization Event | Asset Sale /       | 51% Majority Stake | Acquisition Talks      |
|                      | Full Acquisition   | Acquisition        |                        |
| Strategic Acquirer   | Reliance Retail    | Reliance Retail    | Nykaa                  |
| Strategic Posture    | Brand Reset Under  | Scaled, High-Value | Constrained Runway     |
|                      | Balance Sheet      | Exit               | Sale                   |
+----------------------+--------------------+--------------------+------------------------+
Case Study A: Priyanka Chopra Jonas & Anomaly (The Reset Anchor)
Anomaly established global brand awareness and consumer resonance, yet ran into unit-economic constraints when maintaining an accessible low-cost structure across independent distribution networks. By shifting ownership to Reliance, the brand reset its back-end. It preserved its consumer-facing cachet while trading an independent operational model for an integrated distribution pipeline.
Case Study B: Alia Bhatt & Ed-a-Mamma (The Leverage Anchor)
Alia Bhatt launched Ed-a-Mamma in 2020 as a sustainable children’s and maternity clothing brand. Instead of lingering in direct-to-consumer territory, Bhatt scaled the business rapidly, demonstrating genuine product-market fit and generating roughly ₹150–200 Crore in run-rate:
- In 2023, Reliance Retail acquired a 51% majority stake for approximately ₹350 Crore. YouTube
- Following the partnership, revenues expanded roughly fourfold to touch ₹250 Crore. YouTube
- Bhatt found her corporate anchor while the business had full strategic optionality. The brand plug-in leveraged Reliance’s apparel engine (Trends, Ajio, Avantra), reducing operational friction and multiplying footprint.
Case Study C: Deepika Padukone & 82°E (The Distressed Anchor)
Deepika Padukone launched 82°E in late 2022, targeting the ultra-premium skincare segment with luxury formulations inspired by Indian botanical traditions. Despite Padukone’s tier-one cultural capital, the brand faced severe economic pressures:
- FY25 Revenues: Declined 36% to ₹15.2 Crore. YouTube
- Operating Losses: Stood at ₹12.3 Crore. YouTube
- Marketing Budget: Slashed by 78% to conserve cash runway. YouTube
With the direct-to-consumer path facing unit-economic friction, 82°E entered acquisition talks with Nykaa. Here, the corporate anchor arrived not as a choice made from strength, but out of necessity. When marketing spend dropped 78%, top-line revenues contracted—illustrating what happens when a brand relies primarily on recurring ad spend and founder presence rather than structural retail availability.
For comparative insights on commercial brand portfolio management, explore All Marketing Updates.
Global Benchmarks: Built-In Distribution vs. High-Water-Mark Exits
Examining the international consumer landscape shows that the most commercially resilient celebrity ventures either built strategic retail partnerships directly into their foundations or timed their exits during periods of peak market growth.
+-------------------------------------------------------------------------+
|                  GLOBAL CELEBRITY VENTURE BLUEPRINTS                    |
|                                                                         |
|  MODEL 1: BUILT-IN INFRASTRUCTURE (DAY ONE)                             |
|  • Rihanna + LVMH (Fenty Beauty)  -> 50/50 JV, Sephora distribution     |
|  • Katrina Kaif + Nykaa (Kay Beauty) -> Direct retail JV integration    |
|                                                                         |
|  MODEL 2: HIGH-WATER-MARK EXITS                                         |
|  • Hailey Bieber (Rhode)    -> $1B acquisition at $212M revenue         |
|  • George Clooney (Casamigos) -> Up to $1B exit to Diageo               |
|  • Ryan Reynolds (Aviation Gin / Mint Mobile) -> $2B+ in exits          |
+-------------------------------------------------------------------------+
Model 1: The Day-One Conglomerate Anchor
- Rihanna & Fenty Beauty (LVMH Partnership): Rihanna did not spend years struggling with independent warehousing, third-party contract manufacturers, or regional slotting fees before approaching LVMH. She co-founded the venture inside Kendo—LVMH’s dedicated beauty incubator—taking a 50% equity stake. From day one, Fenty was plugged into Sephora’s global real estate, distribution, and procurement power. YouTube+ 2
- Katrina Kaif & Kay Beauty (Nykaa Joint Venture): Katrina Kaif followed a similar playbook in India in 2019, partnering directly with Nykaa. Kay Beauty bypassed early-stage D2C logistics hurdles, launching straight into Nykaa’s digital ecosystem and national storefronts. The venture operated profitably from inception without relying on emergency bridge rounds. YouTube+ 2
Model 2: Exiting at Peak Valuation Momentum
When founders choose to bootstrap or raise early venture rounds, navigating the timing of an exit is critical:
YouTube
- Hailey Bieber (Rhode): Bieber scaled Rhode through focused, editorially driven product drops, reaching $212 million in high-margin revenue in three years before completing an exit valued at roughly $1 billion. YouTube
- George Clooney (Casamigos): Clooney and partners built Casamigos into a fast-growing spirits label before selling to Diageo for up to $1 billion. YouTube
- Ryan Reynolds (Aviation American Gin & Mint Mobile): Reynolds applied his creative agency, Maximum Effort, to drive rapid top-line expansion, selling Aviation Gin to Diageo (up to $610M) and Mint Mobile to T-Mobile ($1.35B)—clearing over $2 billion in cumulative enterprise value within a single decade[cite: 1].
In all these cases, transactions occurred while revenue trends were expanding rapidly[cite: 1]. The founders negotiated from positions of structural strength[cite: 1].
Reliance Retail’s Strategic Motives: Consolidating India’s $74B Beauty Market
India’s beauty and personal care (BPC) market represents one of the fastest-growing consumer segments worldwide, projected to reach $74 billion by 2035[cite: 1]. Rising disposable incomes, deeper tier-2 and tier-3 urbanization, and the digital expansion of quick-commerce platforms are accelerating consumer spending from unbranded goods to premium personal care categories.
+----------------------------------------------------------------------+
|                      INDIA BPC ECOSYSTEM DYNAMICS                    |
|                                                                      |
|  RELIANCE RETAIL                                                     |
|  • Physical: 19,000+ retail stores across India[cite: 1]             |
|  • Digital/Omnichannel: Tira Beauty, Ajio, JioMart                   |
|  • Strategy: House of Brands (Anomaly, Ed-a-Mamma, internal labels)  |
|                                                                      |
|  NYKAA (FSN E-COMMERCE)                                              |
|  • Base: 42+ million active beauty consumers[cite: 1]                |
|  • Distribution: Specialized retail, dedicated beauty app, Nykaa Man |
|  • Strategy: Category authority, strategic JVs (Kay Beauty, etc.)[1] |
+----------------------------------------------------------------------+
The Conglomerate Race: Reliance vs. Nykaa vs. Tata
Two entities anchor this transformation:
- Reliance Retail: Controls an extensive footprint of over 19,000 physical retail stores across grocery, consumer electronics, and fashion. Through its flagship beauty platform Tira, Reliance is rolling out experiential physical stores alongside a digital shopping app. By acquiring Anomaly and Ed-a-Mamma, Reliance is building a proprietary “house of brands” that cannot be easily matched by outside vendors.
- Nykaa: Operates as a focused beauty destination, serving an engaged community of 42 million registered consumers. Nykaa’s algorithmic curation, high-margin brand partnerships, and consumer trust make it a formidable marketplace.
CONGLOMERATE VERTICAL INTEGRATION:
┌───────────────────────────┐
│     SUPPLIER MARGIN       │  Formulation & Polymer Packaging
├───────────────────────────┤
│    BRAND OWNER MARGIN     │  Anomaly Brand IP & Trademarks
├───────────────────────────┤
│    DISTRIBUTOR MARGIN     │  National Logistics & Warehousing
├───────────────────────────┤
│     RETAILER MARGIN       │  Tira & Reliance Store Network
└───────────────────────────┘
By bringing Anomaly entirely in-house, Reliance captures profits across the entire value chain. Instead of merely taking a retailer margin on third-party products, Reliance now earns the brand owner margin, the distributor margin, and the retail shelf margin simultaneously.
At the same time, owning Anomaly gives Reliance exclusive personal care products to feature across its Tira stores and digital platforms, helping it compete directly with Nykaa and Tata CLiQ Palette.
The Turnaround Blueprint: Capitalizing Anomaly Post-Acquisition
Now integrated into Reliance Retail, Anomaly has access to an established corporate supply-chain infrastructure.
                     RELIANCE TURNAROUND BLUEPRINT
                                  │
         ┌────────────────────────┼────────────────────────┐
         │                        │                        │
         ▼                        ▼                        ▼
  1. Omnichannel           2. Formula &             3. Global Export
     Distribution             Packaging Scale          Corridors
   • Tira Flagships         • Reliance Petrochem     • Middle East & GCC
   • Smart Bazaar /           packaging inputs       • North American
     Reliance Stores        • High-volume domestic     e-commerce
   • Quick Commerce           formulation              distribution
1. Multi-Tier Retail Distribution
Rather than burning capital on stand-alone digital customer acquisition, Anomaly can now leverage Reliance’s distribution network:
- Prestige & Masstige Placement: Anomaly will anchor dedicated shelf displays within Reliance’s Tira physical stores, positioning it directly alongside international prestige names.
- Mass Penetration: Select high-performing, everyday SKUs can enter Reliance’s supermarket ecosystems (Smart Bazaar, Smart Point), unlocking access to middle-class households across hundreds of non-metro cities.
- Quick-Commerce Alignment: Leveraging JioMart and partner networks allows deliveries within hours across major Indian metro centers.
2. Supply Chain Optimization and Vertical Synergies
Reliance’s supply-chain infrastructure offers Anomaly several margin improvements:
- Packaging Efficiencies: Reliance Industries’ position in polymers and petrochemical materials creates immediate economies of scale for Anomaly’s post-consumer recycled (PCR) resin packaging.
- Domestic Production Consolidation: Formulations can be manufactured through optimized, high-capacity Indian facilities, eliminating cross-border logistics costs and reducing currency-fluctuation risks.
- Working Capital Depth: The brand can weather retail inventory holding cycles without taking on venture debt or diluting equity.
3. International Expansion via GCC and Western Retail
The Reliance acquisition does not confine Anomaly to India. Reliance has expanded trade partnerships and consumer footprints across the Middle East, Southeast Asia, and the UK. Chopra Jonas’s international appeal, coupled with Reliance’s capital, positions the brand to re-enter Western and GCC retail spaces on improved commercial terms.
+-------------------------------------------------------------------------+
|                  THE EVOLVING FOUNDER-DIRECTOR ROLE                     |
|                                                                         |
|  PRIYANKA CHOPRA JONAS                 RELIANCE RETAIL VENTURES         |
|  (Creative Director)                   (Operational Engine)             |
|  • Formulation Philosophy              • Raw Material Sourcing          |
|  • Packaging & Aesthetic Identity      • High-Volume Manufacturing      |
|  • Brand Campaign Storytelling         • Real Estate & Shelf Placement  |
|  • Global Media Appearances            • Working Capital & Inventory    |
+-------------------------------------------------------------------------+
Section 8: Core Strategic Takeaways for Operators and Investors
The acquisition of Anomaly provides clear lessons for consumer brands, founders, and institutional investors navigating the creator economy:
+----------------------------------------------------------------------+
|                 THE NEW PLAYBOOK FOR CREATOR VENTURES                |
+----------------------------------------------------------------------+
| 1. AUDIENCE IS AN ACCELERATOR, NOT A MOAT                            |
|    Audience drives trial; operational excellence drives longevity.   |
|                                                                      |
| 2. SECURE THE STRATEGIC ANCHOR EARLY                                 |
|    Partner with distribution powerhouses before runway pressures     |
|    narrow strategic choices.                                         |
|                                                                      |
| 3. VALUE THE BACK-END AS MUCH AS THE FRONT-END                       |
|    Formulation, warehousing, logistics, and retail slotting decide   |
|    whether unit economics compound or crack.                         |
|                                                                      |
| 4. REINVENT THE FOUNDER ROLE                                         |
|    Transition celebrity founders to Creative Directors; allow        |
|    institutional balance sheets to handle the operational burden.    |
+----------------------------------------------------------------------+
- Audience Is an Accelerator, Not an Moat: Initial visibility gets a product into the consumer’s cart once. Formulation consistency, accessibility, and reasonable pricing keep it there. Creator-led brands that treat social capital as a replacement for enterprise logistics eventually encounter operational bottlenecks.
- Find the Anchor Early: The contrasting journeys of Alia Bhatt (Ed-a-Mamma) and Deepika Padukone (82°E) show that the best time to bring in an institutional backer is while top-line performance is rising and strategic choices remain open.
- The Omnichannel Reality: Digital-only D2C strategies face customer acquisition hurdles at scale. Long-term brand durability requires broad physical shelf space, resilient supplier contracts, and scaled distribution networks.
- The Rise of the Operational Co-Founder Model: The future of celebrity entrepreneurship will likely shift away from standalone garage startups toward structured joint ventures. Aligning creative authority with retail operations from day one provides the structural balance modern brands need.
Sources and Reference Documents
Primary Internal Sources (Data & Broadcast Records)
- CNBC-TV18 Financial Broadcast Assessment (2026): Comprehensive television report and digital market bulletin breaking down Reliance Retail Ventures Limited’s acquisition of Anomaly Haircare, including audited 2024 global revenue performance ($50 million), the dissolution of the standalone US corporate entity, comparative performance analysis across Indian celebrity ventures (Ed-a-Mamma, 82°E), and future market growth forecasts across India’s $74B beauty ecosystem[cite: 1].
- National Industry Commercial Bulletin (2026): Formal business report covering Reliance Retail’s acquisition of Anomaly’s intellectual property, trademarks, and global digital ecosystem, establishing Priyanka Chopra Jonas’s continuing governance role as Creative Director, and outlining domestic and cross-border expansion roadmaps across Tira Beauty and international retail hubs[cite: 2].
External Benchmarks & Secondary Literature
- Cosmetify Beauty Index (2023): Celebrity Brand Valuation Models, Consumer Search Volume Metrics, and Digital Media Value Indices.
- Reliance Retail Ventures Limited (RRVL): Corporate Annual Disclosures, Category Portfolio Growth Statements, and Tira Omnichannel Network Strategy Filings.
- FSN E-Commerce Ventures (Nykaa): Financial Year 2024–2025 Audited Reports, Category Growth Metrics, and Corporate Joint Venture Filings.
- Harvard Business Review: The Omnichannel Transition: Why Direct-to-Consumer Brands Eventually Seek Physical Shelf Space.
- LVMH / Kendo Strategic Briefings: The Architecture of Co-Ownership: Evaluating Shared Value Chains in Modern Consumer Brand Building.